Protecting your Medicare information is vital to prevent fraud and identity theft. Learn expert strategies to keep your personal and health data secure.
Medicare & insurance articles to help you make confident coverage decisions
Protecting your Medicare information is vital to prevent fraud and identity theft. Learn expert strategies to keep your personal and health data secure.
Compares Medicare Advantage and Medigap so Texans can tell them apart before enrolling. Covers how each works, what Medicare Advantage typically bundles (dental, vision, hearing, Part D), how Medigap's standardized lettered plans work, and how provider access, costs, dental coverage, and prescriptions differ between them. Ends with who each option tends to suit and a Medigap enrollment-timing note, targeting best Medigap insurance in Texas and Medicare Advantage plans in Texas with dental.
Navigating health insurance options can be confusing, especially when you're turning 65 or already on Medicare. Discover the crucial differences between the Health Insurance Marketplace and Medicare.
Medicare Advantage plans evolve annually, bringing new benefits, costs, and networks. Learn what changes to expect and how to ensure your coverage still fits your needs.
Explains the importance of what follow your Doctor and medication instructions is important.
Navigating Medicare Supplement plans can feel overwhelming. Discover which Medigap plans offer the best coverage for your healthcare needs and budget.
Confused about how the Affordable Care Act impacts your Medicare coverage? Discover the key differences and how these two major health laws work together to protect your health and finances.
Turning 65 doesn't always mean you need to enroll in Medicare right away, but it also isn't a decision to leave to assumption. If you don't have qualifying coverage and delay anyway, the penalty can follow you permanently, not as a one-time fee. Here's what the Initial Enrollment Period actually means, and why it deserves its own conversation separate from Medicare's annual fall window.
Choosing a Medicare plan involves more than comparing premiums and extra benefits. Learn six important factors to consider, from your doctors and prescriptions to costs, travel, and how you actually use your healthcare.
A zero-premium plan is a Medicare Advantage plan that has no monthly premium (other than the Medicare Part B premium). In other words, you don’t pay anything to the insurance company each month for your coverage. More than three-quarters of Medicare Advantage enrollees are in zero-premium plans
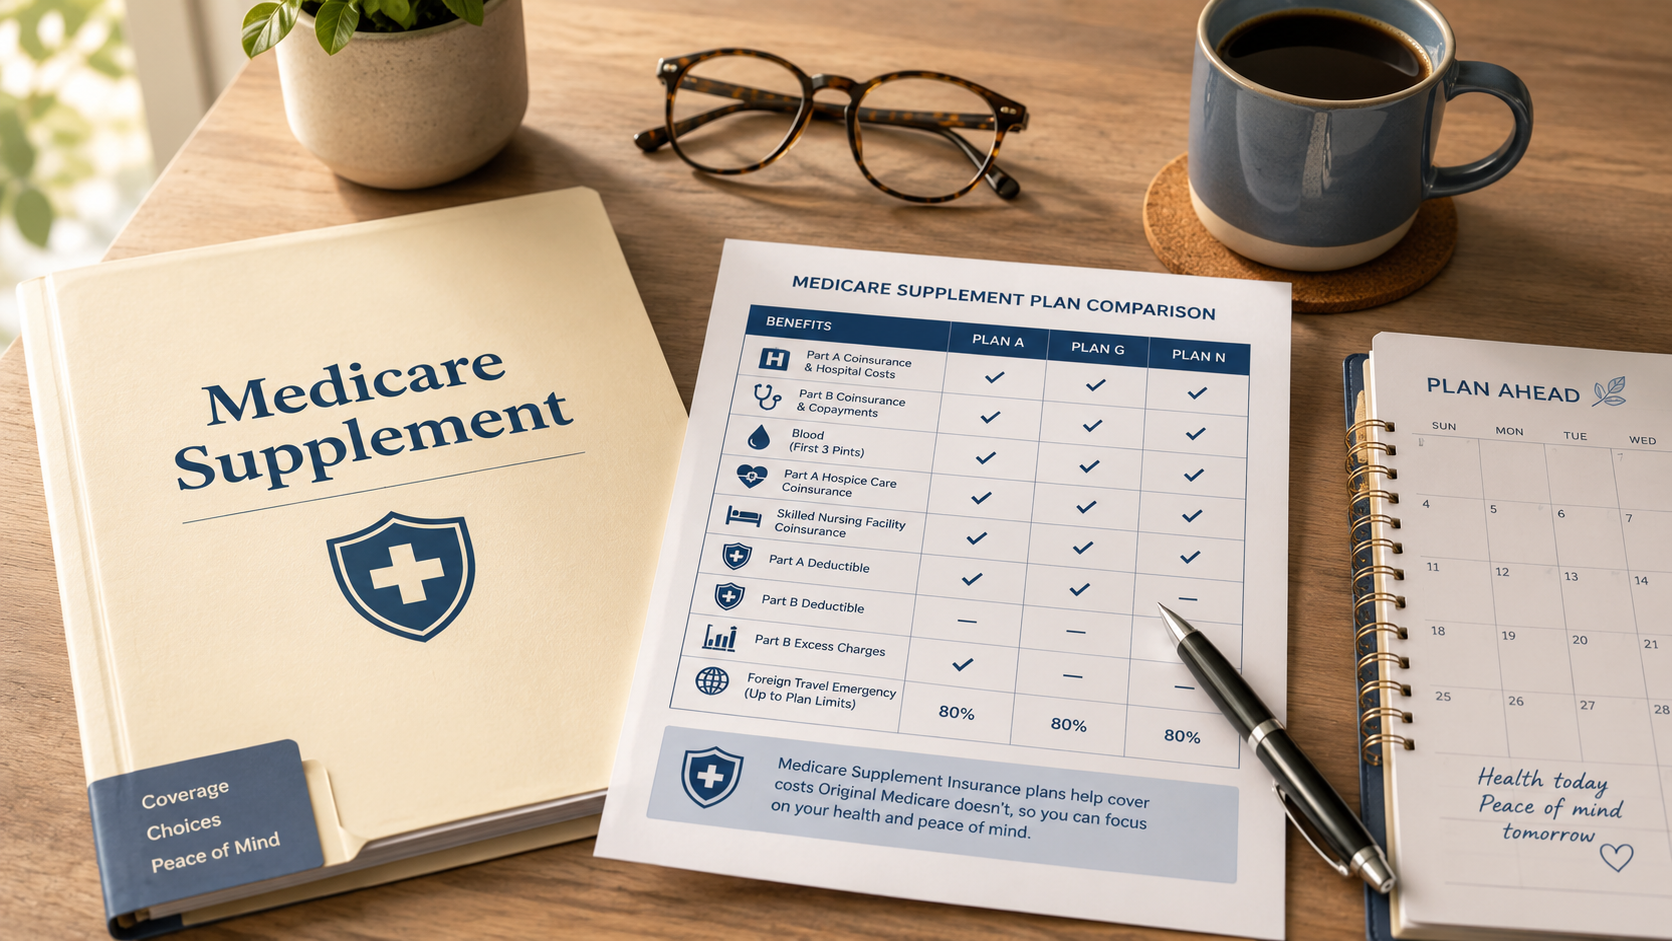
Confused about Medicare's gaps? Learn how Medicare Supplement plans provide crucial coverage, offering peace of mind and financial protection for your healthcare needs.
Medicare's Annual Enrollment Period runs October 15 to December 7. During this window, beneficiaries can switch plans, change Part D coverage, or confirm their current plan still fits. Miss it, and for most people, those changes aren't available again until next year. The piece frames this as a deadline worth planning for calmly, not scrambling through in the final days.
There's no universal right answer to Medicare, only the right fit for you. After 20 years as a nurse, I watched people thrive on plans that would have frustrated someone else entirely. Here's what I wish every Medicare beneficiary understood before they choose, and why the decision you make now can shape your options years down the road.
Medicare Advantage plans can be a great option for some Medicare Beneficiaries. Now, let’s get started and take a look at what Medicare Advantage can offer you at a basic level.
In planning your Medicare insurance coverage when you are around your age of 65 there is importance of knowing what your coverage choices are before you enroll in any insurance plan.
After 20 years as a nurse, I learned there's no universally 'better' Medicare choice. I watched Original Medicare and Medicare Advantage each work well, and each create friction, depending on the person's doctors, health, and needs. Here's what I saw at the bedside about access, referrals, and continuity of care, and why the right plan is the one that fits you, not the one that sounds best in a commercial.
Most people spend decades planning for retirement, Social Security, 401(k)s, paying off the house, but never think of Medicare as part of that plan. After 20 years as a nurse, I watched families realize too late that Medicare was never designed to cover long-term custodial care. Here's why I believe Medicare belongs in the retirement conversation, not just the healthcare one.
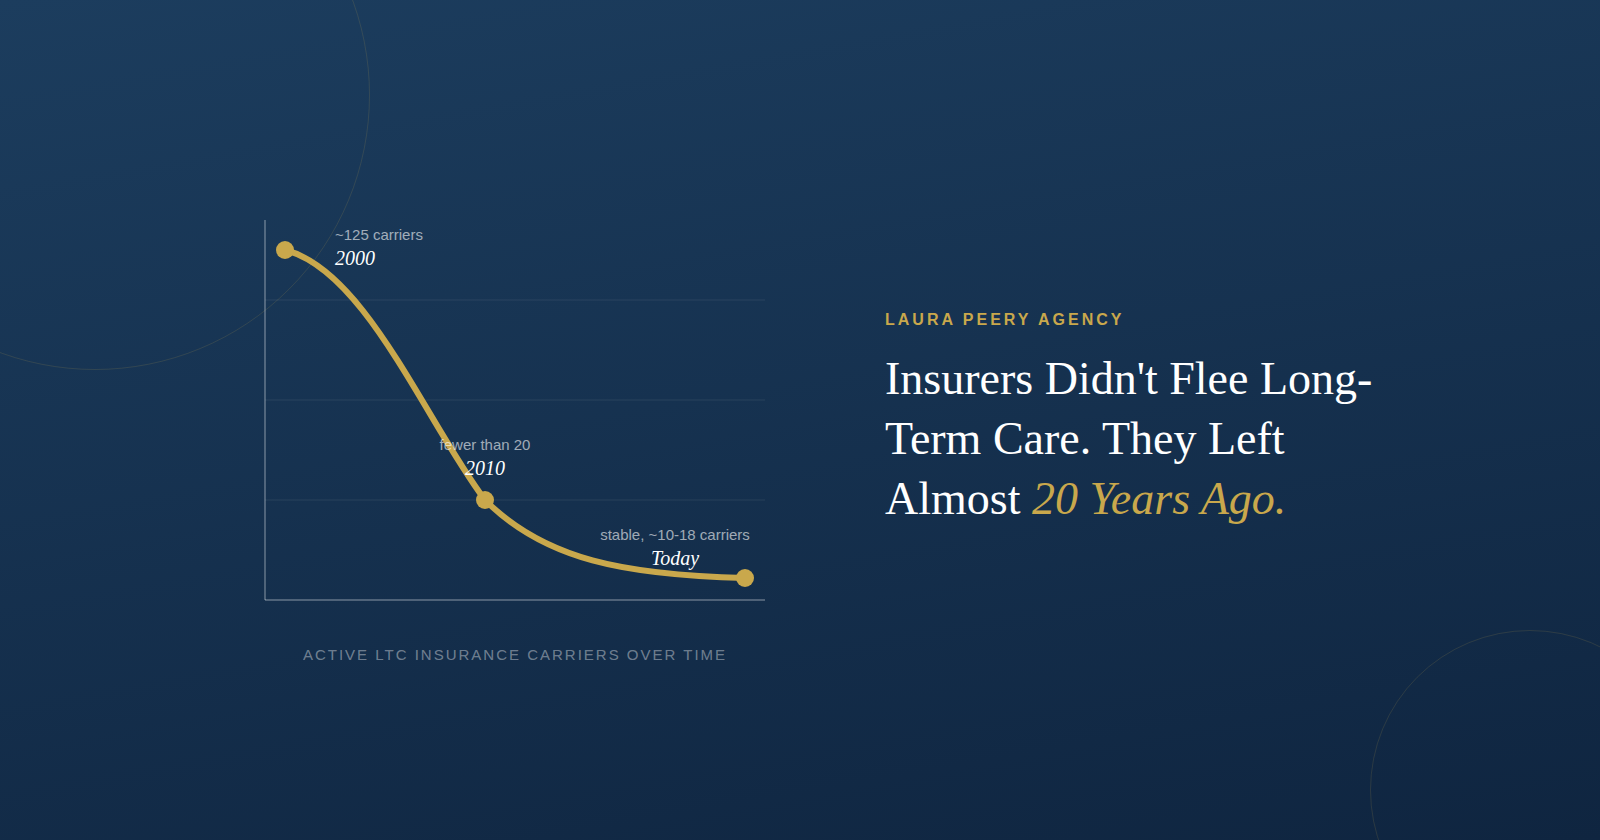
See current 2026 costs for home care, assisted living, memory care, skilled nursing, and adult day care — and how to plan ahead with Laura Peery Agency LLC.
Does the Government Pay for Long-Term Care? What Medicare and Medicaid Actually Cover
You have to take into account all the factors that effect your Medicare Supplement premiums.
Being healthy at 65 can make Medicare feel simple, but this may be the time when you have the most choices. Here’s why it’s worth thinking ahead before choosing a Medicare Supplement.
Let's talk about high-deductible Medicare supplements, which might just be the perfect alternative to Medicare Advantage plans for you.
Medicare Open Enrollment is here! Discover the crucial mistakes many seniors make and how to avoid them to ensure you pick the best plan for your needs.
Confused about Medicare Supplement? This guide simplifies key benefits and comprehensive coverage options, empowering seniors to make informed healthcare decisions.
Medicare Advantage has gained popularity with Medicare Beneficiaries.
Medicare Advantage, which is commonly known as Medicare Part C, is an option you can enroll in once enrolled in Original Medicare Part A and Part B.
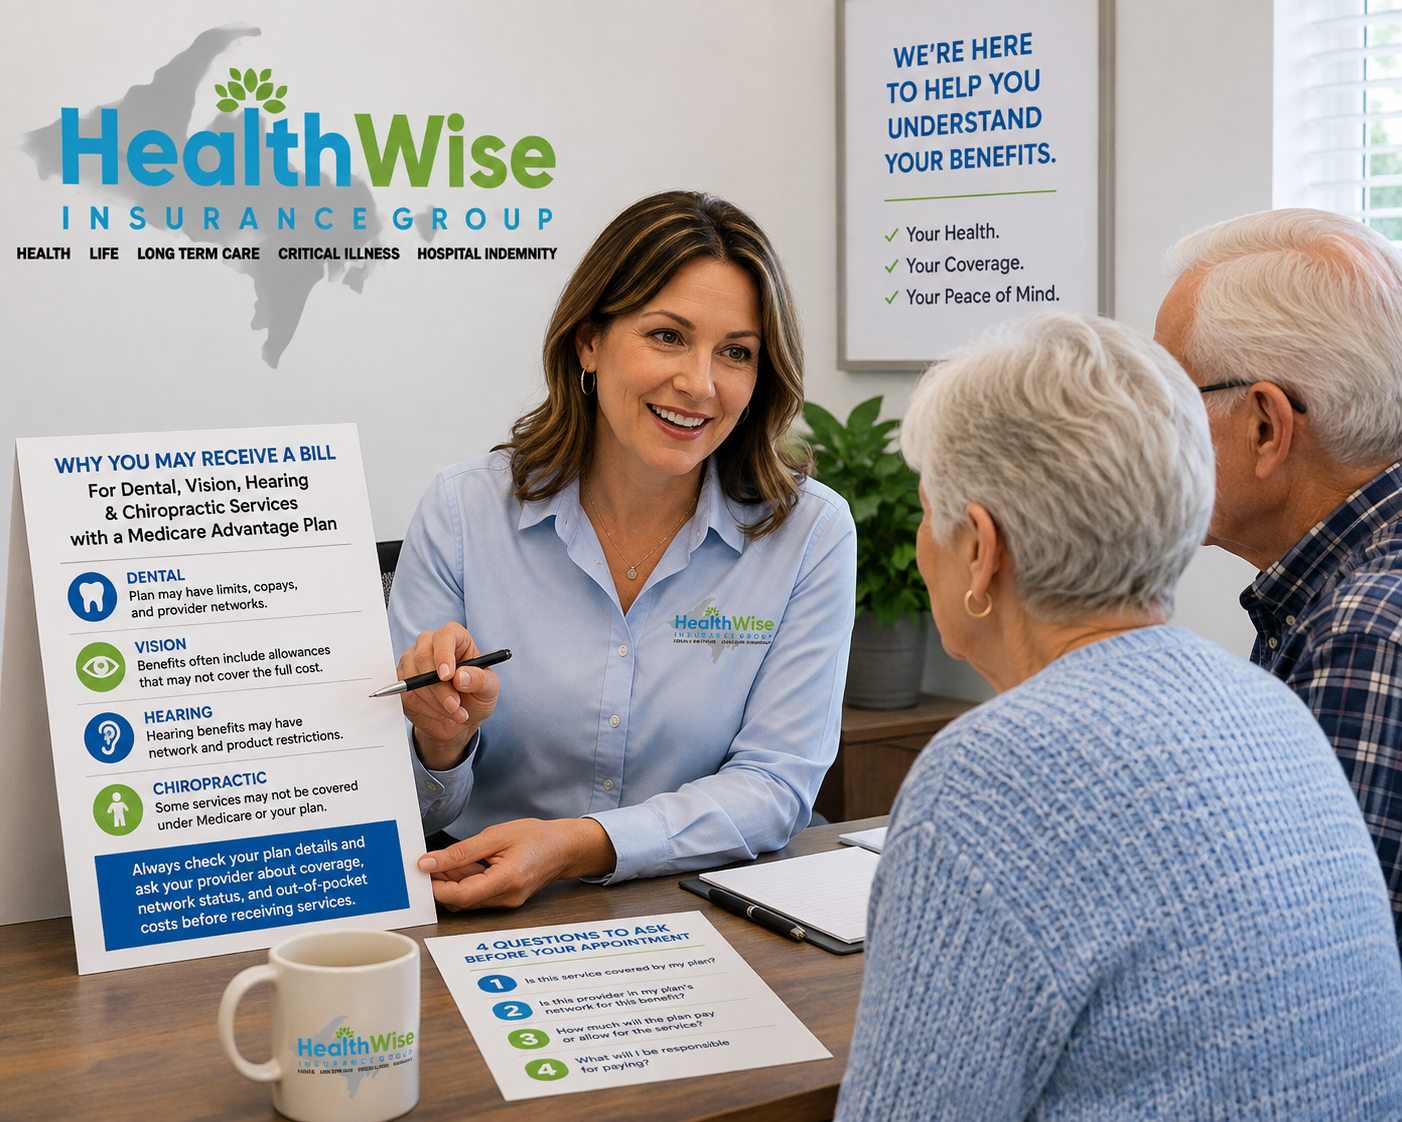
One of the most attractive features of many Medicare Advantage Prescription Drug (MAPD) plans is the additional benefits they may provide beyond Original Medicare. Depending on the plan, these benefits can include routine dental care, eye exams and eyewear, hearing aids, and additional health and wellness services. These benefits can be extremely valuable. However, they can also create confusion when a Medicare beneficiary receives a bill after being told that a service was “covered.”